What We Do and Do Not Do for Insurance Claim Help
We build the record of the damage and the work. You own the claim. This table is the line we hold on every job.
| We do | We do not |
|---|---|
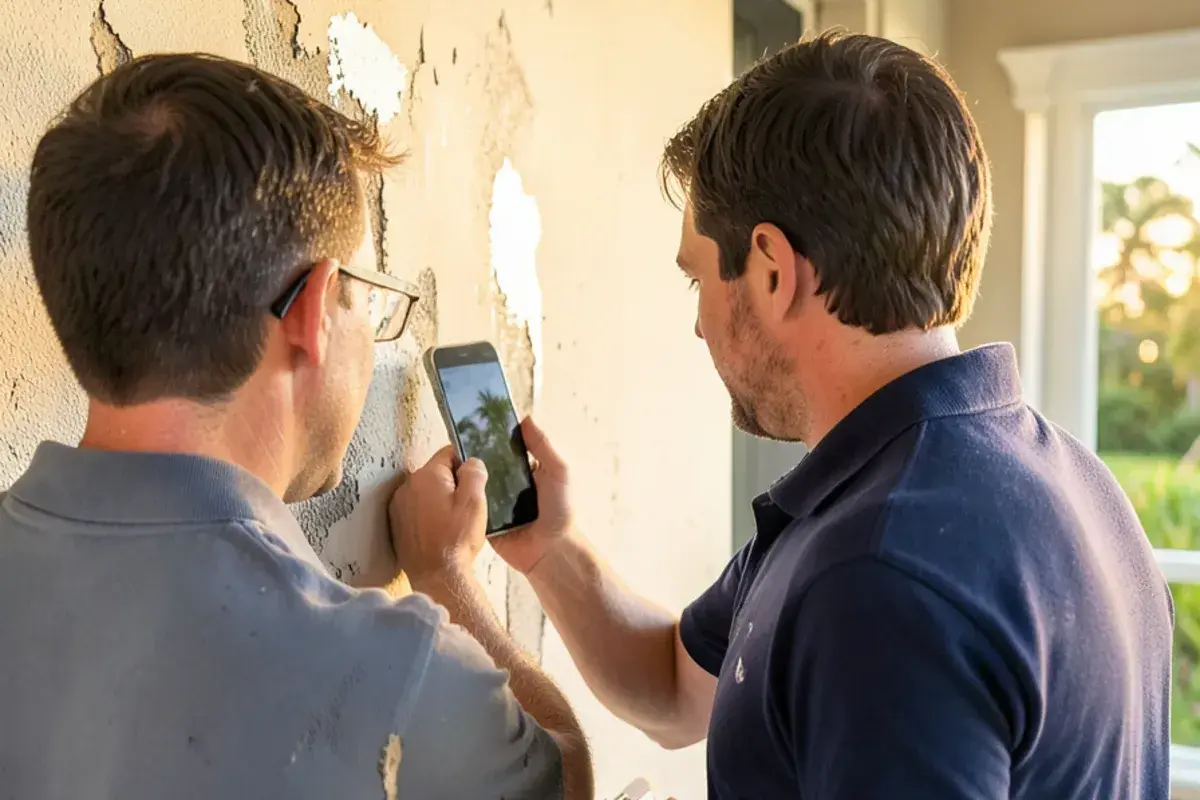
| Photograph the damage before demolition | Read or interpret your policy |
| Log moisture readings and keep a moisture map | Tell you what is or is not covered |
| Keep equipment records showing what ran and for how many days | Negotiate with your insurer |
| Write an itemized estimate | Adjust, prepare or file your claim |
| Explain our own estimate to you or your adjuster | Act as a public adjuster |
| Walk you through the steps of filing, if you decide that is best | Promise that any amount will be paid |
In practice, claim help from us means water damage documentation and plain process steps. If you are still deciding whether anything needs doing, start with a free damage assessment.
When Does a Water Loss Become a Claim Question?
Usually on the day you find the water. Around St. Augustine that tends to mean a failed supply line, an appliance leak, rain driven in by a storm, or tide water. We cannot tell you how your policy treats any of them. We can record the facts your adjuster may ask about.
- The source: what failed or where the water came in
- The date you found it, written down that day
- How far it traveled, on a moisture map
- The water category, from Category 1 to Category 3
Start before cleanup, because marks on walls fade as a house dries.
Why Does Florida Limit What a Contractor Can Do on a Claim?
Florida separates the repair trade from claim handling. F.S. 489.147 bars a contractor from interpreting policy provisions, advising on coverage or duties, or adjusting a claim without a public adjuster license. F.S. 626.854 adds that a contractor may not offer or perform public adjuster services.
The same statute leaves two doors open. A contractor may suggest you contact your insurer about a proposed repair, and may discuss or explain its own bid. Everything we do on a claim fits through those two doors.
Be careful with any company that offers to take the claim off your hands. Ask what it means by that, then ask your insurer or the DFS helpline.
Ask any company for its license number and check it on the DBPR site, ours included.
Where Should Coverage Questions Go?
Take every coverage question to someone allowed to answer it. Each of these has a different job.
- Your insurer or its adjuster: what your policy says and how the claim is being handled.
- A licensed public adjuster: someone you hire to work your claim for you.
- An attorney: legal advice on your policy, a denial or a dispute.
- The Florida Department of Financial Services consumer helpline: free state help with insurance questions and complaints.
F.S. 627.7142 names that helpline in the Homeowner Claims Bill of Rights, a summary insurers must send personal lines policyholders within 14 days of first hearing about a claim. It also describes mediation through the Department. Read it when it arrives.
Water on the floor and a claim to think about? Call Dal.
Open 24 hours for emergencies. Non-emergency calls are best between 7am and 7pm.
- 5.0 on Google, 8 reviews
- Family owned since 2020
- Calls go straight to the owner
- Free assessments and estimates
Request a free estimate
Not an emergency? Send the details and we will call you back. If water is still moving, call instead.
How the Process Runs From First Call to Final Records
The order below keeps the record intact and leaves every claim decision with you.
- Stop the source if it is safe, and stay clear of wet electrical. Then call us any time with an emergency. Calls go straight to the owner.
- Take your own phone photos before moving anything.
- Consider contacting your insurer now, and ask whether it wants to see the damage before work starts. Filing is your decision.
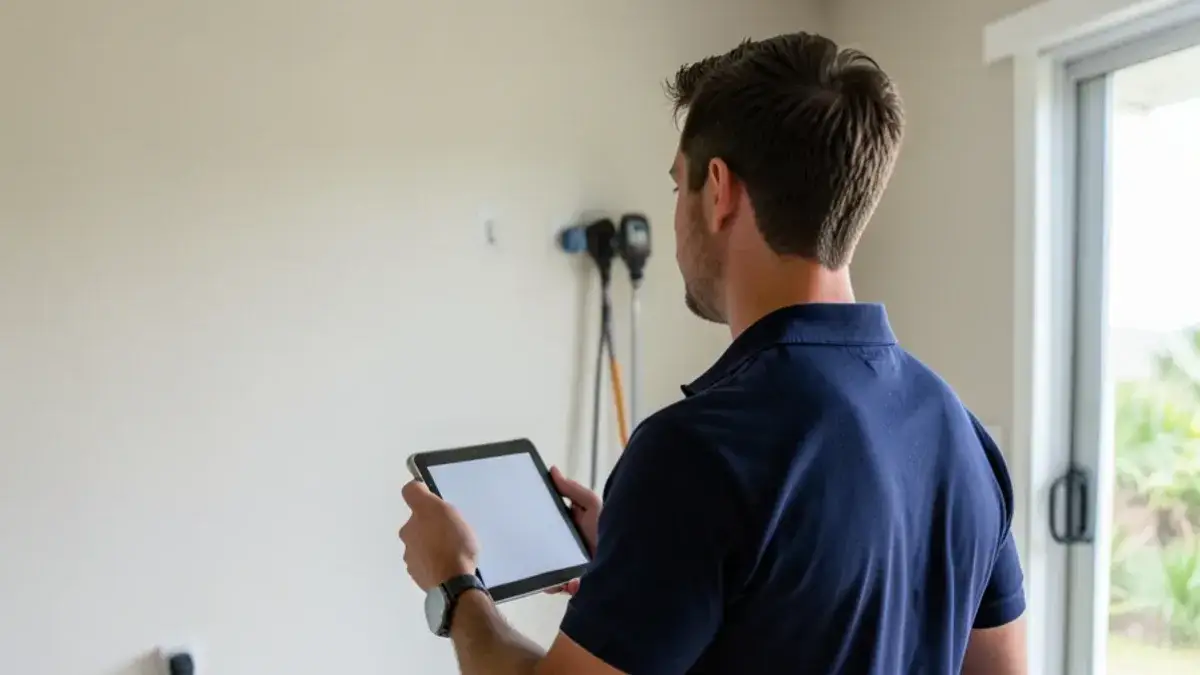
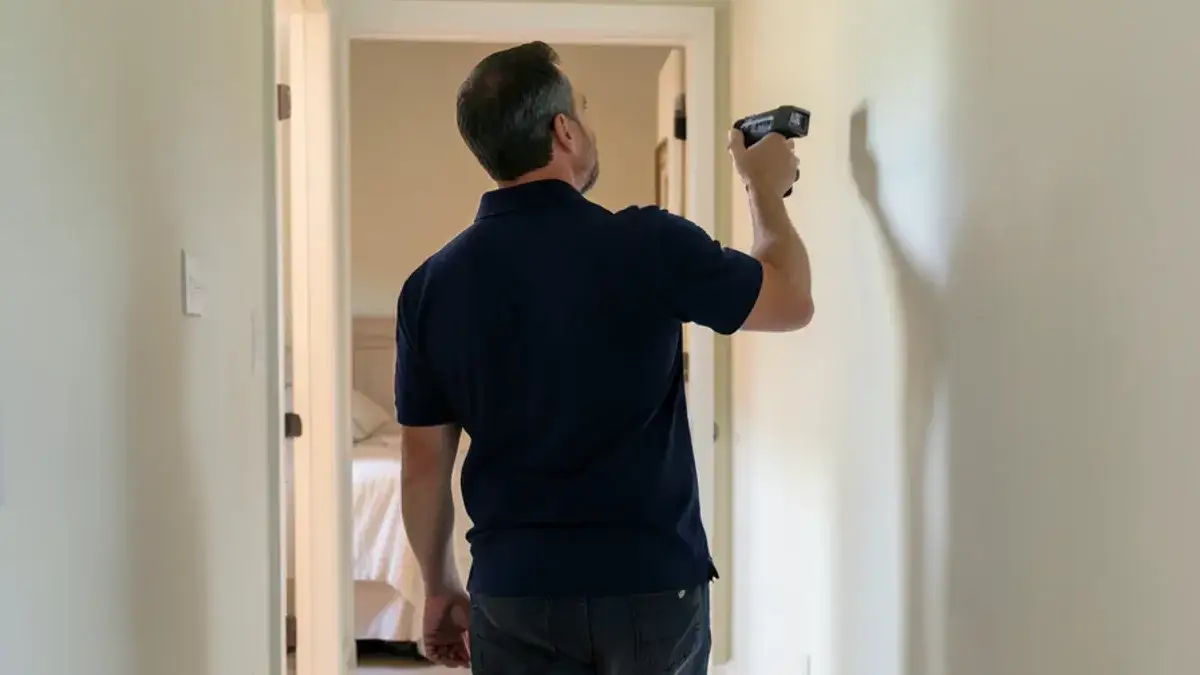
- We assess with moisture meters and thermal imaging and photograph before demolition. You receive a written scope and itemized estimate before heavy work.
- We extract, then dry with air movers and LGR dehumidifiers, logging moisture readings every day until materials reach the dry standard.
- You get the records and choose who receives them. If your adjuster has questions about our estimate, we answer them.
Florida Claim Dates Set by Statute
Know these dates exist, then confirm how they apply to you. They are general Florida law. Your policy wording and your adjuster decide your claim.
| Date | Time limit | Source |
|---|---|---|
| Notice of a new or reopened claim | One year after the date of loss | F.S. 627.70132 |
| Notice of a supplemental claim | 18 months after the date of loss | F.S. 627.70132 |
| Date of loss for a hurricane | The date of landfall | F.S. 627.70132 |
| Insurer acknowledges your communication | Within 7 calendar days, with exceptions | F.S. 627.70131 |
| Insurer inspects the property | Within 30 days of proof of loss | F.S. 627.70131 |
| Insurer pays or denies | Within 60 days of notice, with exceptions | F.S. 627.70131 |
Write down your date of loss the day you find the water. After a storm season along the Matanzas River, weeks blur together fast.
What Moves the Estimate, and Who Is Responsible for the Bill?
You are responsible for the work you approve. Our assessment and estimate are free, and they are never tied to making a claim. We come out, look at the damage and write an estimate, with no pressure either way.
These factors move the number:
- Square footage and how many rooms or floors got wet
- Water category, since Category 3 adds removal and cleaning
- Materials, such as hardwood, tile, drywall or insulation
- Equipment days for air movers and LGR dehumidifiers
- Demolition, and any put-back of drywall, paint or flooring
Put-back is priced separately, and it often runs higher here, where finishes tend to cost more.
We never promise that an insurer will pay any of it. Your deductible is between you and your insurer. Waiving it, absorbing it or helping with it is not something we offer.
Why Homeowners Call 1 Call for Claim Records
Choose us for the job, and the records come with the way we work.
- A family-owned company founded in 2020. Dal Beggs and his son run it.
- Your call goes straight to the owner, not a call center.
- Daily readings and photos are kept as the job runs, not rebuilt afterward.
- We say plainly what we cannot do, so you know where to take each question.
What customers say
5.0 stars on Google from 8 reviews. Quoted as written.
“Highly recommend Dal and his team at 1 Call Restoration - great locally owned company. We had a pipe burst that flooded parts of our home - it was such a stressful situation for our family. Dal and his team were amazing through the whole process. They helped us get everything cleaned up and even helped us as we worked with our insurance. Super thankful for their expertise, quality work, responsiveness, and professionalism.”
Our service area spans six Northeast Florida counties, from St. Augustine Beach and St. Augustine Shores to World Golf Village and Palm Coast. When drying is the urgent part, start with water damage mitigation.
Inside insurance claim help
Frequently asked questions
Can you tell me whether my policy covers this water damage?
No, and Florida law is the reason. F.S. 489.147 bars a contractor from interpreting policy provisions or advising on coverage. We can tell you what is wet, how the water moved and what the work involves. For what your policy pays, ask your insurer, a licensed public adjuster or an attorney. The Department of Financial Services helpline also takes insurance questions.
Will you speak to my adjuster about the damage?
Yes, about our own work. Your adjuster can ask why a wall was flood cut, what the moisture readings showed, or how a line on our estimate was built, and we will explain it. That conversation stops at our estimate. We do not argue coverage, negotiate an amount or speak for you on the claim itself.
Do you fill out or file claim forms for me?
No, you file the claim yourself, or through a licensed public adjuster or attorney if you hire one. F.S. 626.854 treats preparing, completing or filing a claim for pay as public adjuster work. We give you the photos, moisture logs, equipment records and itemized estimate, and you decide what to do with them.
Do I have to open a claim before you start extraction?
No, our visit and estimate never depend on a claim, and many people call us before deciding. Whether to file is your decision alone. Before heavy work begins, consider calling your insurer to ask whether it wants to see the damage first. We photograph every room before demolition either way, so the original condition stays on record.
What happens if the insurer's estimate is lower than yours?
We walk through our line items with you or your adjuster, and that is the limit of our part. Closing the gap is not something we do, because that would be negotiating a claim. A licensed public adjuster or attorney can act for you. F.S. 627.7015 also sets up a mediation program for disputed property claims, and the DFS helpline can explain it.
Can I sign my insurance benefits over to a restoration company?
Not under newer policies. F.S. 627.7152(13) says a policyholder may not assign post-loss benefits under a residential or commercial property policy issued on or after January 1, 2023, and an attempted assignment is void. We do not ask for one. Your agreement with us covers the work, and the claim stays between you and your insurer.
Need the damage recorded before cleanup starts? Call us now.
Open 24 hours for emergencies. Non-emergency calls are best between 7am and 7pm.
- 5.0 on Google, 8 reviews
- Family owned since 2020
- Calls go straight to the owner
- Free assessments and estimates
1 Call Restoration, Saint Augustine, FL. (208) 464-4194.
Related services
Worth reading
Where we handle insurance claim help
See all of our service areas.